A cash on delivery store can be profitable and still run out of money. The two are separate questions, and most sellers only discover the second one at the worst possible moment: the week after their best week.
The reason is timing. You pay for the ads today, you pay the supplier today, the courier collects the cash a week later, and the courier pays you a week after that. Every order you add widens that gap before it closes it. Growth consumes cash.
This article puts numbers on the gap, shows how to work out your own, and explains what the remittance cycle does to a scaling store.
What a remittance cycle is
When a customer pays the driver, that money does not go to you. It goes to the courier. The courier banks it, reconciles it against the parcels they say they delivered, and transfers it to you on a schedule. That schedule is the remittance cycle.
Cycles across the markets where cash on delivery is normal fall roughly into three bands:
| Cycle | Typical of | What it means for you |
|---|---|---|
| 2 to 4 days | Mature local couriers, larger accounts | Close to working capital neutral |
| 7 to 10 days | The common case | One to two weeks of spend financed by you |
| 14 to 30 days | New accounts, small volumes, some regional carriers | You are lending the courier your ad budget |
The number in your contract is not always the number you get. Count from the day the customer paid to the day the money cleared your account, over at least ten transfers, and use the average. Disputed parcels, failed deliveries awaiting a second attempt and public holidays all stretch it.
The arithmetic on a profitable month
Take a store doing 1,200 orders a month at 46 in local currency, 14 product cost, 3.20 shipping, 11 in ads per order, with a 72% delivery rate. That store is profitable:
| Line | Amount |
|---|---|
| Orders placed | 1,200 |
| Delivered | 864 |
| Returned | 336 |
| Revenue collected | 39,744 |
| Product, shipping and return costs | 16,608 |
| Ad spend | 13,200 |
| Profit | 9,936 |
Now the cash. Ads are paid daily, roughly 440 a day. With a 10-day remittance cycle, there is always about 4,400 of your own money sitting in the courier’s account. That figure is not profit and it is not a loss. It is the float, and you cannot spend it.
Nothing above is wrong with the business. The store earns 9,936 a month and holds 4,400 permanently out of reach. If your bank balance is below that figure, you are one slow transfer away from pausing your ads.
Why scaling makes it worse before it makes it better
Double the ad spend and the float doubles immediately. The extra revenue arrives one cycle later. For the length of one cycle you are paying twice as much and receiving the same amount.
| Day | Daily ad spend | Daily remittance | Daily cash movement |
|---|---|---|---|
| Before scaling | 440 | 1,325 | +885 |
| Day 1 after doubling | 880 | 1,325 | 445 |
| Day 10 after doubling | 880 | 1,325 | 445 |
| Day 11 onward | 880 | 2,650 | +1,770 |
The hole is about -4,448 and it is real money, needed on day one, returned on day 11. Sellers who scale on a Thursday and check their bank on the following Tuesday conclude the campaign is failing. It is not. The money is in transit.
This is also why the advice to scale gradually is more than caution. A 20% increase digs a hole a fifth the size, and the cycle fills it before the next increase.
Returns are the second drain, and they are slower
A returned parcel costs you the outbound shipping, the return shipping and the ad that produced it. At a 28% return rate that is 336 parcels a month. The money was never collected, so nothing comes back on the remittance. The cost is paid immediately and recovered never.
If you could lift delivery from 72% to 80% by confirming orders before dispatch, this store would deliver 960 parcels instead of 864 and collect 4,416 more in the same month, with the same ad spend. That is the single biggest cash lever a cash on delivery store has, and it is covered in detail in how to raise your COD confirmation rate.
How much float do you actually need
A workable rule: hold enough cash to cover one full remittance cycle of ad spend, plus one week. Work it out in two steps.
- Average daily ad spend, measured over the last 30 days, not budgeted.
- Your real remittance cycle in days, measured from customer payment to cleared funds.
Multiply them, then add 25%. The margin covers a public holiday, a disputed batch and one courier paying late. A store spending 440 a day on a 10-day cycle needs about 5,500 permanently available before it is safe to scale.
If you cannot hold that, the options are to shorten the cycle, lower the spend, or raise the proportion of orders that are paid before dispatch.
Three ways to shorten the gap
Negotiate the cycle, not only the price
Couriers compete on price per parcel because that is the number sellers ask about. The remittance cycle is negotiable too, and at volume it is often easier to move. Going from 14 days to 7 halves your float for free. Ask for it at renewal, with your volume in hand.
Offer a discount for paying now
A customer who pays by card at the moment of ordering costs no float, no return shipping and no failed delivery. That is worth paying for, and a discount of a few percent is usually less than what the alternative costs you. The arithmetic is specific to your margins, so work it out rather than copying a number.
Split your couriers
Running two couriers is not only a hedge against one failing. If they remit on different schedules, money arrives more evenly through the month instead of in two lumps, which makes a smaller float stretch further.
Reconciling what the courier says against what you sold
Every remittance statement should be checked against your own orders. Three discrepancies are common, and all three cost money quietly:
| What you see | What it usually is | What to do |
|---|---|---|
| Parcel marked delivered, no cash on the statement | Driver collected and it was not reconciled | Query within the courier’s dispute window, usually short |
| Parcel marked returned, customer says they received it | Mis-scanned, or a second attempt not recorded | Ask for the signature or delivery proof |
| Amount collected lower than the order total | Driver accepted a part payment or applied a discount | Compare against the order; this should never happen silently |
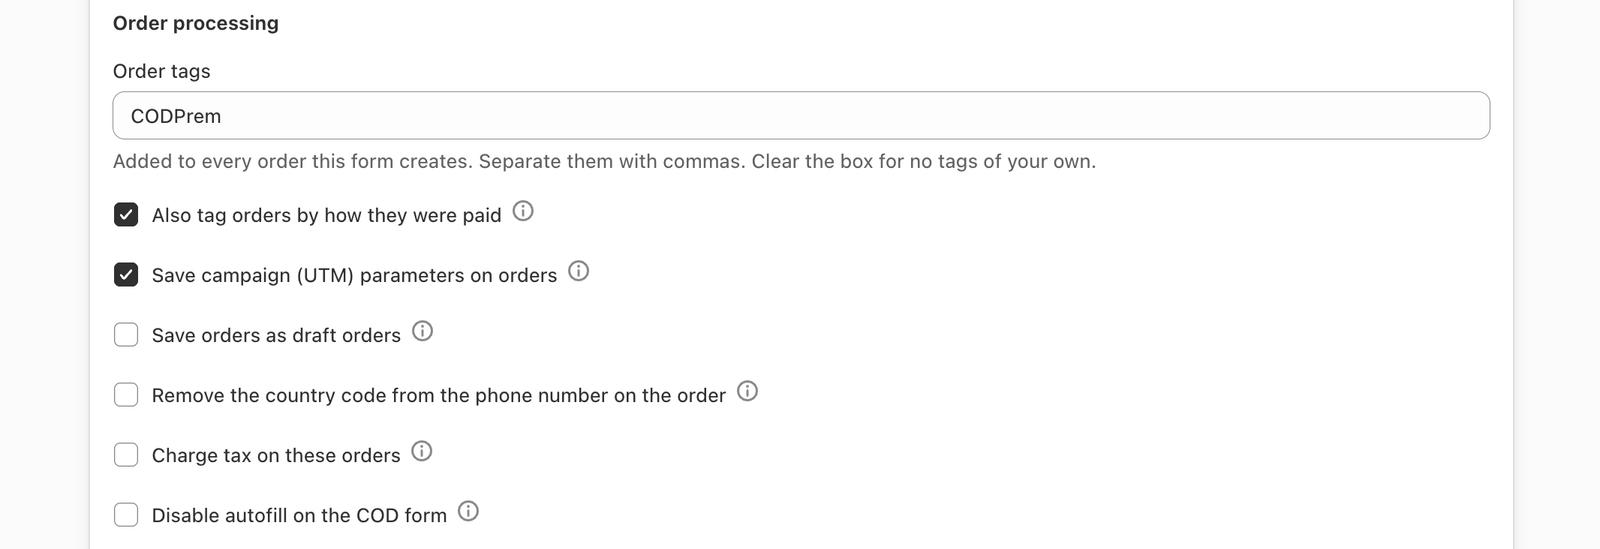
Doing this needs your own order list in a form you can filter and sort. If your orders arrive from several sources, make sure the ones placed through your cash on delivery form carry a tag so they can be isolated in one click.
What to measure every month
| Figure | Where it comes from | Why it matters |
|---|---|---|
| Average remittance days | Your bank statements against delivery dates | The multiplier on everything below |
| Average daily ad spend | Ad platform, last 30 days | Decides the size of the float |
| Delivery rate | Delivered divided by orders placed | Every point is money that never has to travel |
| Cash locked in transit | Daily spend times cycle days | The number that must be in the bank |
| Unreconciled amount | Statement against your own orders | Small each month, large each year |
The short version
Profit tells you whether the business works. Cash flow tells you whether it survives the month. In cash on delivery the two diverge because the courier holds your revenue for a week or more while you keep paying for ads.
Measure the real cycle, hold a float that covers it, scale in increments the cycle can absorb, and spend your effort on the delivery rate, because an order that does not come back is the only order that never needed financing in the first place.
For the full per-order arithmetic that sits underneath all of this, see what a cash on delivery order really earns.